Charter Schools offer an alternative way for education to be provided to the next generation. A key hurdle can be raising the funds needed to start such a school. Impact Investing could offer a solution to this.

This approach involves individuals investing for impact – in other words, instead of donating or giving money to the cause of setting up the new Charter School, they invest in a legal structure which will allow them to have financial return while also enabling impact.

The way this works is:

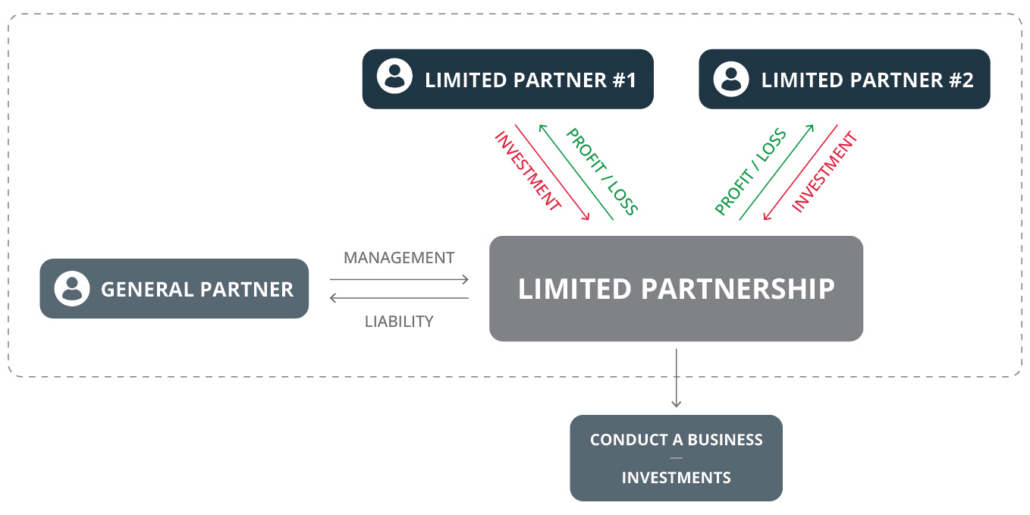
  • Individuals invest into a limited partnership structure. In the diagram below these individuals are shown at the top of the diagram.
  • There is a general partner which is a company who actually runs the limited partnership.
  • In this case, the subject of the limited partnership is the new school.
  • Over time the school receives income and becomes sustainable after the initial kick-start from investors, and so is able to provide financial return to the investors.

Limited partnerships are a corporate structure that combine some key features of companies (such as separate legal personality) and partnerships (such as tax pass-through treatment).

Each situation will be unique and different, but this model could provide an alternative approach to allow a new Charter School to get off the ground. It might even be that institutional investors might be interested in investing, or religious organisations if there is an alignment of beliefs with the proposed school.

It is important to ensure compliance with fundraising rules (administered by the Financial Markets Authority), such as ensuring investors qualify as wholesale investors, or come under another exemption. Also, if it were to be open to retail (such as parents) then it would be more complicated.

An alternative to this would be to introduce a charitable entity, such as a trust, which could also play a role in such a structure as the owner of the general partner.

We have expertise in this and other legal structure types and would be happy to discuss the options available. Reach out to our experienced team here.
 

The information contained in this outline is of a general nature, should only be used as a guide and does not amount to legal advice. It should not be used or relied upon as a substitute for detailed advice or as a basis for formulating decisions. Special considerations apply to individual fact situations. Before acting, clients should consult their Parry Field Lawyer.

If your organisation is listed on Schedule 32 of the Income Tax Act 2007 and you are thinking about a name change, the good news is that the process is more straightforward than many people assume. Here is a practical overview of what is involved.

What is a Schedule 32 entity?

Schedule 32 status gives qualifying charities, whose purposes are mainly overseas, the ability to issue receipts to their donees for donations made to the charity. The donees can use those receipts to claim a credit or deduction against their income tax.

Can a Schedule 32 entity change its name?

Yes. There are generally no restrictions from Inland Revenue’s perspective on a Schedule 32 entity changing its name. However, there are a couple of practical considerations to keep in mind. The proposed name also should not create confusion for the public by being too similar to another existing organisation.

Does the legislation need to change first?

Ultimately, yes, to formally update Schedule 32 to reflect the new name, an amendment to the legislation is required. That means the change needs to be included in a Parliamentary Bill, which then goes through the full legislative process. This can take time.

However, the legislative update does not need to happen before your organisation starts using the new name. In practice, once the name has been changed on the relevant registers (the MBIE register and the Charities Service register), your organisation can start operating under the new name right away.

What about IRD?

Once the register updates are done, you or your adviser should notify IRD’s operational team. You can do this through myIR or by emailing charities.queries@ird.govt.nz. IRD will then update their systems to reflect the new name for tax purposes and will also update the Approved Donee Organisations list on their website.

The legislative amendment to Schedule 32 can then be progressed in due course. IRD’s policy team can initiate that process, but it is important to let them know the new name as soon as possible. IRD has noted that they sometimes do not hear about name changes until years after the fact, which can cause complications.

Summary

In summary, the process would roughly follow the these steps. Firstly, consider your new name and receive advice on whether it is likely to be approved. If the new name will likely be approved, then proceed with updating your name on the MBIE and Charities Service registers. Once that has been done, then you can notify IRD’s operational team via myIR or the charities queries email. Also make sure IRD’s policy team are informed, so the Schedule 32 legislative amendment can be initiated. From this point the legislative change can follow in due course and does not hold up the name change itself.

We can help

If your organisation is considering a name change and you would like advice on the process or any related legal matters, we would be happy to assist. This article is a general guide only and is not intended as legal advice. Please get in touch with our team if you would like to discuss your specific situation.

For many people, the idea of philanthropy and immigration feel like separate worlds. But under New Zealand’s Active Investor Plus Visa, they can go hand in hand. If you are looking to relocate to New Zealand and want your investment to do some good along the way, this visa pathway is worth understanding.

Note: as at 29 May 2026, there have been changes to philanthropic investments for the Active Investor Plus (AIP) Visa. Read more here. 

What Is the Active Investor Plus Visa?

The Active Investor Plus (AIP) Visa is designed for wealthy individuals who want to invest in New Zealand and, in return, gain the right to live here indefinitely. It is open not just to the applicant but also to their partner and dependent children aged 24 and under. As with most residence visas, applicants need to be of good health and character and be considered a fit and proper person.

Two Ways to Invest

There are two categories under this visa, and the one that allows philanthropic donations is the Balanced Category.

The Growth Category requires a minimum investment of NZD $5 million, which must go into managed funds or direct investments into New Zealand businesses. Philanthropy is not an option under this category.

The Balanced Category requires a minimum of NZD $10 million but opens the door to a much wider range of investments, including listed equities, bonds, property development, managed funds, direct investments and, importantly, philanthropy.

Note that previously, there was a maximum cap of $7.5 million for philanthropy, but now the total required investment can be invested into philanthropy.

The different requirements for both categories can be seen in this table below.

Growth Category Balanced Category
Minimum investment NZD $5 million NZD $10 million
Acceptable investments Managed funds, direct investments Listed equities, philanthropy, bonds, property development, managed funds, direct investments
Time to invest 6 months from Approval in Principle (with option to extend 6 months) 6 months from Approval in Principle (with option to extend 6 months)
Retention period 36 months 60 months
Time in New Zealand Minimum 21 days over investment period Minimum 105 days over investment period (reductions available)
Checkpoints 24 and 36 months 24 and 60 months


What Counts as a Philanthropic Investment?

Not every charitable donation will qualify. It must meet the criteria set out in the immigration operational manual instructions. To be considered an acceptable investment for the purposes of the Balanced Category, the funds donated as part of this visa must go to organisations that are a registered charity with at least two years of annual returns filed, and that hold current Inland Revenue donee status.

Donee status is granted by Inland Revenue to organisations that use at least 75% of their funds on charitable or public good purposes within New Zealand. It is the same status that makes donations tax-deductible for ordinary New Zealanders, so it is considered an indicator of legitimacy.

One thing to be aware of is that Immigration New Zealand does not maintain a list of approved charities for this purpose. That means the responsibility sits with you and your advisers to confirm that any organisation you intend to support meets both criteria before funds are committed.

A Meaningful Way to Invest

For investors who are drawn to giving back, the Balanced Category offers an opportunity to combine residency with purpose. New Zealand has a strong charitable sector, and directing a portion of a $10 million investment toward an established, compliant charity is a rewarding way to meet the visa requirements.

You can find out more details on the New Zealand immigration, and trade and enterprise websites.

If you are considering this pathway and want to understand how philanthropic giving might fit into your overall investment structure, we would be happy to help you work through the detail. You can reach out to our experienced team here.


This article is provided for general informational purposes only and does not constitute legal advice. The information provided may not be applicable to your specific circumstances. You should seek independent advice from a qualified New Zealand lawyer before making any investment or immigration decisions.

Independence on a charity board is essential for building trust and promoting transparency. It supports good decision-making by providing objective oversight and managing potential conflicts of interest, giving stakeholders confidence that the charity’s choices are genuinely in its best interests. A common question is: how many independent board members are needed when a company becomes a charity?

There is no universal rule, but becoming a charity represents a significant shift in mindset. In a private company, a small group of people may hold multiple roles such as, directors, shareholders, and employees, without much public scrutiny. Once an entity registers as a charity, the organisation exists to advance charitable purposes for the public benefit and ideally continues beyond the founders’ involvement. Registration brings benefits such as tax concessions and credibility, but it also entails greater accountability, transparency, and public scrutiny.

Risks of a Non-Independent Board

If the same individuals act as directors, shareholders, and employees, conflicts of interest can arise, particularly regarding remuneration, contracts, or other benefits. For example, it is inappropriate for people to decide their own salaries or employment terms. Any remuneration should be set at market rate, and those receiving it should not participate in the decision-making process.

Managing Conflicts of Interest

Charities Services’ guidance explains that conflicts of interest can be actual, potential, or perceived, and may be financial or non-financial. While conflicts are common in charities, poor management can lead to disputes, bad decisions, or reputational damage.

To manage conflicts effectively, a charity should:

  • Maintain a clear conflict of interest policy and an interests register
  • Ensure conflicts are declared at the start of meetings
  • Exclude conflicted individuals from discussions or decisions
  • Record how conflicts are handled in the minutes
  • Report significant conflicted transactions as related party transactions in the financial statements

Practical Guidance on Board Composition

For a company converting to a charity, it is generally expected that around half the board be truly independent. This ensures that conflicted individuals can step aside from decisions affecting their own pay or position while leaving enough independent members to make valid decisions.

Our experienced team help many charities with their governance. If you would like to talk through your situation, feel free to reach out.

A Privacy Law change which affects all organisations in New Zealand has was implemented in May 2026. In this article we outline what it means and why it matters.

The change – indirect information

The change boils down to “IPP3A”, which is an acronym that refers to an addition to the third privacy principle (collection of information). As a reminder, the privacy obligations in New Zealand are overseen by the Office of the Privacy Commissioner and consists of several privacy principles contained in the Privacy Act 2020.

Those 13 privacy principles cover how an organisation collects data, who it tells about that, how people can update their information and more. We outlined exactly what they are and how they work in this overview. A few years ago, when the Privacy Commissioner visited and ran a seminar at Parry Field, he summarised everything with “don’t be creepy”, which is still the best summary we’ve heard when it comes to the approach to collecting private information.

This new addition privacy principle helps to clarify and strengthen the collection and notification obligation to “indirect” information. Essentially what this means is that if your organisation collects information indirectly about someone and stores it, then you have to let them know unless an exception applies

When would this apply?

The Privacy Commissioner gives this example in their helpful guidance here – obviously adapt it for your context and business or charity, but you can see the general principle that emerges:

 “Sally makes a claim to her insurance company, Trusted Insurance Co, about damage to her car. She tells them she has taken it to Mater’s Motors for repairs. Trusted Insurance Co asks Mater’s Motors for information about the damage to the car, including whether they thought Sally was responsible for the damage. Mater’s Motors view on whether Sally was responsible for the damage is personal information about Sally. Trusted Insurance Co has indirectly collected Sally’s personal information.”

In this case the insurance company will now have an obligation by taking “reasonable steps” to notify Sally about what it collects about her including (this list is the summary from the Privacy Commissioner’s site).

  • the fact that the information has been collected,
  • the purpose of the collection,
  • the intended recipients of the information,
  • the name and address of the agency that is collecting the information and the agency that holds the information,
  • if the collection is authorised or required by law, which particular law, and
  • their rights of access to, and correction of, their information.

It is worth taking a few minutes to pause and consider if there is any part of your organisation which might collect such information indirectly about people. If so, how do you let people know?

In limited circumstances, an organisation may not be required to notify the individual concerned – for example: if information is publicly available information.

Do you need to disclose where you collected the information from?

If you have collected information indirectly, there is no requirement to disclose where you collected the information from you will always need to be considering what information you collect and why (see IPP 1 and 2 for more information about this).

Some final reflections / challenges since you have read this far relating to privacy:

  • Do you have a privacy officer in your organisation?
  • When was your policy last reviewed and updated?
  • Have you thought through what you would do if there was a hack of your data and it got disclosed?

We often help organisations with their privacy-related questions. If you would like to discuss your situation or would like assistance to create a bespoke privacy policy for you, feel free to reach out to our team.

Recent changes to the Charities Act 2005 (amended by the Charities Amendment Act 2023) requires all registered charities to review their ‘governance procedures’ at least every three years. The first three-year cycle ends in October 2026 – so this is quickly approaching! This article explains why regular governance reviews matter, not only for legal compliance but also for making sure an organisation’s structure reflects how it operates, and outlines the key documents charities should check, from founding rules and officer records to employment agreements, volunteer arrangements, board charters, and policies.

While this requirement is only for registered Charities, we think that any organisation, especially ones that handles funds, has volunteers or employees or is a party to contracts, should regularly review and keep up their rules and governance procedures up to date. This is important from a legislative and compliance perspective, but also to ensure the governance and structure of an organisation accurately reflects day-to-day operations.

Part of a thorough governance review is looking over records and documents and ensuring that changes and decisions are well-recorded and accurate.

So, what sort of record and document considerations might your Charity need to look over?

Amendments to your rules

  • Have you amended your Charity’s founding document since it was created? If so, are there clear and accurate records of the rules that the Trust holds, and are the same uploaded to Companies Office and Charities Services (where needed)?

Officers

  • Have you changed Officers since the Charity was created or more recently, if it was set up long ago? If so, are there clear and accurate records of who the Officers were/are, and when any changes in leadership occurred? Does the Trust hold these documents, and is Charities Services updated with the changes (where needed)? We can assist in clarifying what is needed with these steps.

Employees and volunteers

  • Are your employment agreements up to date and reflective of current law?
  • If you have volunteers, do you have any agreements and how to keep track of their voluntary service with your Charity?

Board charter

  • Board charters are an excellent way of clearly and concisely setting out responsibilities, roles and procedures of a Charity. For example, you could set out your mission/purpose, the stakeholders or communities you engage with, and how meetings are run. If you don’t have a Board Charter, we recommend creating one. It doesn’t have to be complex or lengthy – just reflective of your organisation. If you do have a Board Charter already, consider revisiting it, and checking whether what is set out is accurate and reflects the organisation and the direction it is heading in. 

Policies

  • We recently released a series of these – find out more here.

We can Help

Parry Field lawyers are well-experienced in assisting organisations review, amend, and update their governance procedures and policies. Please reach out to our Impact Team if you would like to discuss how we can assist your organisation.

For more information about the requirement to review governance procedures under the 2020 Amendment to the Charities Act 2005 please see here.

We are often called on to assist incorporated societies with disputes. This is why the Incorporated Societies Act 2022 requires all incorporated societies to have a dispute resolution procedure.

While a procedure is a great starting point, on its own it is not a silver bullet. In this article we discuss why and offer practical tips on disputes.

What disputes do we see?

The most common disputes we see are due to:

  • People interpreting the rules differently due to ambiguity in the constitution. Where there is ambiguity, there is room for different and even contrasting interpretations and therefore conflict.
  • Officers simply not following the society’s constitutions. This is a fundamental obligation and failure to do so can raise the ire of members and prompt actions to remove officers.
  • Personality and behaviour clashes between members or between members and officers, or between officers.
  • Officers pursuing opposing agendas, leading to conflict within the Committee.

What are the consequences

There is often an emotional toll for people involved and for the wider society. We have seen lifelong friendships destroyed and societies wound up. When lawyers are required, there is also a financial cost for the society that will likely be borne by the society as a whole.

How to prevent disputes

Here are our top tips for avoiding disputes:

  1. Have a clear constitution – Remove ambiguity from your constitution.
  2. Follow the rules – The rules bind members and officers. If the rules are no longer fit for purpose, change them, but avoid simply not following the rules because they are inconvenient.
  3. Communicate well – Members are at the heart of incorporated societies. Keep members informed of what decisions have been made and why. In our experience, the greater the transparency, the higher the trust.
  4. Set behaviour expectations – Constitutions (rules) generally focus on what to do without much focus on behaviour. Consider using a Code of Conduct to set out behaviour expectations, or embed these in the constitution. Consider making it an obligation of membership to adhere to specific behaviours.

How we can help

We can help by updating constitutions and drafting a Code of Conduct. We can also advise on the best way to communicate with members on sensitive matters. Reach out to us if you would like to discuss your situation.

If the dispute escalates, our disputes team is highly skilled in seeking the best legal outcome.

Increasingly, Trustees are asking whether they might become personably liable. This is an excellent question and one that all officers of charities should consider.

We were recently asked whether Trustees can be held personally liable if a Trust becomes insolvent. The short answer is yes, in certain circumstances. However, there are some protections which can limit liability and it will depend on what action the Trustees took. For example, if there was some dishonest action, Trustees could be liable, but for genuine decisions this is less likely.

These principles would also apply to officers of other entity types such as to officers of incorporated societies or directors of charitable companies.

Inbuilt protections for Trustees

Our trust deed limits the liability of Trustees using indemnity clauses like this:

No Trustee hereof will be liable for any liability or expense arising from any cause whatsoever when acting with the authority of the Board and will be entitled if the Trustee has paid the expense or discharged the liability out of the Trustee’s own funds, to reimbursement from the Trust Fund.

However, this is usually followed by wording like this:

UNLESS such liability or expense arose from the Trustee’s dishonesty, wilful misconduct or gross negligence or was incurred without authority from the Board.

In other words, if a Trustee is dishonest, engages in wilful misconduct or gross negligence, or creates liability without the approval of the Board, the Trustee may be held liable. This makes sense – liability limitations exist to ensure Trustees are not unreasonably held accountable for their decisions, while at the same time requiring them to avoid poor behaviour.

 If you would like help to create or amend a trust deed, please contact us.

Can insurance help?

Trustee insurance (often called Directors and Officer Liability Insurance) policies may help but often exclude the insolvency of the Trust and any dishonest activities by Trustees.

Insolvency

If the Trust is unable to pay its debts it may apply for voluntary liquidation under section 24 of the Charitable Trusts Act 1957 (“CTA”). A creditor or Official Assignee (a government-appointed person responsible for managing liquidations) may also apply to the Court for the liquidation of the Trust under section 25 of the CTA. In either situation, section 301 of the Companies Act 1993 may apply, and interestingly, this may apply to Trustees as well as Directors of Companies.

Section 301 permits the court to require Trustees to personally repay money or return property, or pay compensation if it appears to the Court that a Trustee “has misapplied, or retained, or become liable or accountable for, money or property of the company, or been guilty of negligence, default, or breach of duty or trust in relation to the company.

While we have not seen any case law about section 301’s application to Trustees specifically, it is useful to be aware that this is a possibility in certain circumstances.

How do Trustees protect themselves?

In many respects, Trustees have similar responsibilities to directors of companies when it comes to insolvency. They need to pay close attention to their financial situation and understand if they are reaching a point when they may not be able to pay their creditors. We recommend:

  • Paying close attention to the financial situation.
  • Asking, “Will we be able to pay for the contracts we have with creditors?” If you are unsure, avoid entering into the contract.
  • If insolvency is looming, seek professional advice urgently.
  • Consider whether you should contact IRD to explain the situation. IRD and employees rank highly among creditors. IRD often initiates liquidation proceedings.

 In a nutshell

  • Trust Deeds indemnify Trustees for certain matters. These do not include dishonesty, wilful misconduct or gross negligence or taking steps without authority from the Board.
  • Insurance usually excludes insolvency.
  • If a Court determines a Trustee has misapplied, or retained, or become liable or accountable for, money or property of the company, or been guilty of negligence, default, or breach of duty or trust in relation to the company, the Trustee may be personally responsible for reimbursement.
  • Trustees must understand the Trust’s financial circumstances and make decisions that will avoid insolvency.

We can help

We have acted for hundreds of charities and can help your charity as well. Please contact us for specific advice on Trustee liability for your circumstances and how to prevent it.

Many of the same good governance principles apply across all sectors. However, being on a charity or for-purpose board means facing added challenges to those in the commercial sphere. By considering the unique dynamics of charity boards, this article aims to present essential lessons to improve governance in practice, based on helping many hundreds of such groups as the most active law firm in this area.

The unique dynamics of charity boards

Charity boards must find a balance between promoting organisational and public interests and charitable purposes. While board members with expertise in finance, law, or governance are valuable, without a strong understanding of the charity sector and their organisation’s work, their governance may have limited success.

This is particularly so as charity governance is often grounded in ethical or values-based considerations. For example, if a board takes actions which don’t align with values or goals, this can undermine the organisations foundation and reputation. This is particularly detrimental in a sector where maintaining strong stakeholder relationships is key to success. Additionally, where activities are seen as inherently virtuous there can be a lack of organisational accountability.

Key challenges for charity boards

Let’s unpack a few of the key challenges for charity boards:

  1. Role blurring – a common place where things go wrong in charity governance is the blurring of lines between governance and management roles. This creates risk of board members being pulled into day-to-day operations. Although in smaller organisations it is common for people to wear multiple ‘hats’ (often as volunteers), issues arise where the board becomes too concerned with management. To avoid this, clearly define the role of board members to prevent a pull into day-to-day operations and stay focused on the board’s strategic goals.
  2. Legal considerations and checking of rules – along with governance best practice, for many charitable organisations there are specific officer or trustee duties to be complied with under New Zealand law. Additionally, the Charities Act now requires boards to review their rules every three years and ensure they are fit for purpose. For more information see our Charities Handbook and this article on reviewing rules.
  3. Measuring success and impact – this may be difficult in a sector where impact is often qualitative and long-term, making navigating organisational direction difficult.
  4. Aligning organisational and board development – governance must keep pace with organisational growth and goals and aim to keep growing.
  5. Structuring onboarding and reflection – set out clear objectives and ensure regular evaluation of performance. This should include continuing to assess and improve governance practices. A clear board charter will also offer overall guidance – setting out role, relationships, how decisions are made, procedures, inductions, committees.
  6. Understanding your organisation’s purpose – this will help guide decision making, assess the effectiveness of governance, and navigate further growth and goals. Consider, do all your board members say the same thing when asked about purpose?
  7. Balancing professionalism and idealism – in purpose driven organisations this may be particularly difficult amongst board members with different backgrounds.

We help many charities with their governance – let us know if you would like to talk through your situation.

The deadline for incorporated societies to re-register under the Incorporated Societies Act 2022 was 5 April 2026. If your society has not re-registered, the consequences of missing the deadline are serious.

This article outlines what happens for those societies that failed to re-register, and what options are available if that occurred.

The consequences of failing to re-register

Societies that did not re-register by the deadline were removed from the Incorporated Societies Register on 5 April 2026. The practical consequences of this are significant:

  • The society will no longer be able to operate as a legal entity.
  • All assets, including property, will need to be disposed of in accordance with the society’s constitution.
  • The Registrar may step in and direct how assets are distributed, overriding decisions that would ordinarily be made by members or committee members.
  • Banks will freeze society’s accounts and refuse officers access, making it difficult to pay employees or meet other financial commitments.
  • Existing contracts including as leases or supplier agreements may be affected, as the entity named in those arrangements will no longer legally exist.

Can a society be reinstated after removal?

Yes, but it involves time, cost, and a period of ongoing uncertainty.

Under the 2022 Act, a society can apply for reinstatement on the ground that it was operating at the time of removal and there is a proper reason for it to continue to exist. This is the most relevant ground for societies that simply missed the deadline.

To apply, the society (or a member, creditor, or other eligible party) will need to provide the societies latest financial statements (if not already filed), confirmation the society has at least 10 members, contact details, and evidence of operation. Evidence of operation can include things such as financial records, meeting minutes, or legal documents. The society will also need to pay a restoration fee of $177.78 plus GST. Applications for this can be made online through the Incorporated Societies Register.

Importantly the society must also submit a constitution that complies with the requirements of the 2022 Act, read more about these requirements here.

Once an application is accepted, it is publicly notified, and there is a 20 working day period during which objections can be made. If no objections are received, the society will generally be restored the following working day.

It is worth bearing in mind that the Companies Office is likely to receive a large volume of reinstatement applications, and there are time frames mentioned above, which mean it will not be quick.

What should your society do now?

If you have missed the deadline and are uncertain about your society’s options, we encourage you to get in touch with us. We can help you understand the reinstatement process and take steps to get your society back on track as quickly as possible.

If you have been successfully reinstated, please see here for more information on the 2022 Act and what obligations and responsibilities your Society has.